Crypto Insurance Underwriting Evidence: Proof & Claims Guide
Understand the standards of crypto insurance underwriting evidence required to substantiate digital asset claims, verify control, and satisfy insurer requirements.
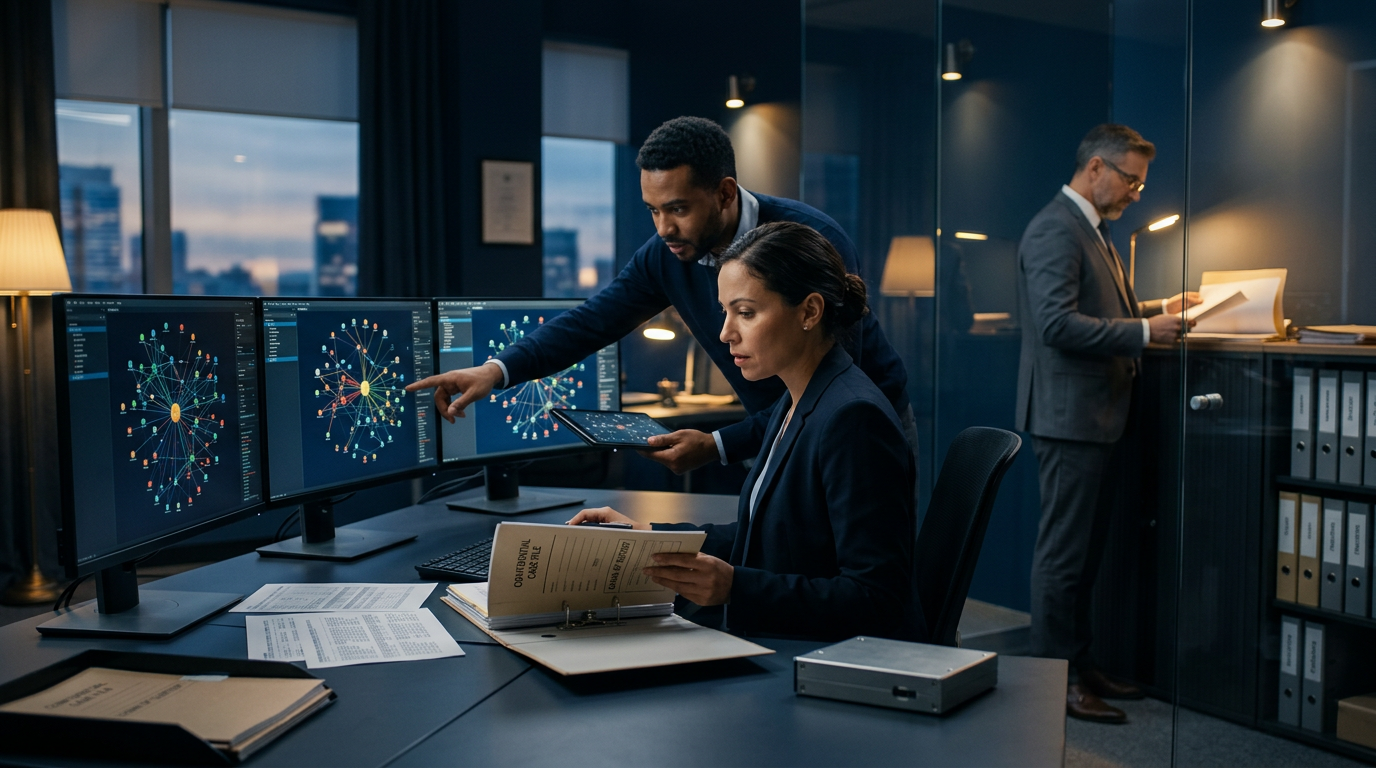
When an enterprise treasury, exchange, custodian, or high-net-worth individual suffers a catastrophic loss of digital assets, securing coverage payouts hinges entirely on the quality of proof provided to claims assessors. Evaluating crypto insurance underwriting evidence requires a rigorous synthesis of on-chain data, hardware security module (HSM) telemetry, operational logs, and strict legal chain of custody. Underwriters do not simply accept wallet account balances or self-reported incident summaries; they mandate verifiable forensic proof establishing exactly how, when, and through what operational vulnerability a compromise took place.
Navigating digital asset coverage claims requires institutional policyholders and legal teams to understand the exact evidentiary threshold underwriters demand. Whether dealing with crime policies, specie insurance, or cyber risk riders, establishing bulletproof documentation is the single defining factor in claim determination. Aegis Financial Forensics provides independent technical investigations through specialized blockchain forensic engagements designed to satisfy insurer audit standards and withstand legal scrutiny.
Crypto Insurance Underwriting Evidence: Scope and Impact
Digital asset insurance policies represent highly specialized legal contracts that bridge traditional commercial crime standards with complex cryptography. Unlike conventional property insurance—where physical damage is visually inspectable—crypto insurance claims rely on electronic records, cryptographic signatures, and distributed ledger events. The scope of underwriters' technical scrutiny touches every layer of an organization's digital architecture, operating environment, and internal control policies.
This analytical process impacts several key stakeholder groups across the financial and legal landscape:
- Institutional Asset Managers and Treasuries: Entities holding Bitcoin, Ethereum, or collateralized stablecoins must maintain ongoing evidence of key management practices, multi-signature threshold approvals, and segregation of duties to satisfy policy warranties.
- Custodians and Exchange Operators: Custodians operating hot and cold wallet infrastructure face strict reporting requirements following a security breach, needing to prove that unauthorized withdrawals bypassed defense protocols without internal collusion.
- Insured High-Net-Worth Individuals: Individuals holding high-value wallets covered under personal asset riders must prove absolute initial ownership, non-negligent storage of private seed phrases, and unauthorized external transaction execution.
- Private Counsel and Risk Officers: Legal professionals guiding clients through notice-of-loss filings must frame evidence in accordance with governing policy language, state insurance codes, and formal evidentiary standards.
Understanding what constitutes admissible technical proof prevents claim denials based on mischaracterized exploits, policy exclusions, or unverified asset ownership claims.
The Claims Verification Process: How Underwriting Analysis Works Step by Step
Substantiating a claim requires executing a structured, step-by-step forensic reconstruction of the event. Underwriting technical experts follow a strict protocol to verify whether an event constitutes a covered peril (such as external hack, rogue employee theft, or safe depository breach) or falls under excluded conditions (such as protocol design flaws, bad trades, or unverified internal fraud).
- Notice of Loss and Operational Isolation: The policyholder issues an immediate notice of loss to the carrier while simultaneously isolating affected systems. Technical teams extract volatile RAM state, preserve firewalls, and record API interaction logs before systems are rebooted or reconfigured.
- On-Chain Transaction Reconstruction: Forensic experts map the entire movement of compromised funds starting from the primary source address. Utilizing specialized analytical tools and direct blockchain node analysis, investigators document transaction hashes, block timestamps, gas fees, and target deposit addresses.
- Key Management and Access Log Verification: Underwriters review the technical configuration of the affected wallets. If the asset was protected by a multi-signature framework (e.g., 3-of-5 threshold), investigators pull audit trails from hardware modules, key management systems (KMS), and employee identity management platforms to determine which specific signatures were compromised.
- Independent Forensic Synthesis: Investigators cross-reference network events with our established blockchain forensic methodology to produce a formal, unalterable technical report detailing the breach vector, asset path, and current disposition of stolen funds.
Failing to execute these steps correctly during initial incident response frequently causes permanent evidentiary gaps. Inexperienced victims often commit fatal mistakes—such as wiping infected servers or failing to preserve network packets—that prevent carriers from confirming loss authenticity. Reading our breakdown of mistakes that destroy crypto fraud evidence can assist teams in avoiding catastrophic log destruction early in an incident.
What Evidence Exists Following a Digital Asset Loss
Submitting a successful insurance claim requires assembling a comprehensive evidentiary package combining on-chain ledger records with off-chain system telemetry. Insurers rely on independent forensic accountants and cryptographic experts to verify that the claimed loss represents actual financial damages caused by an external or covered internal breach.
1. On-Chain Ledger Telemetry
The primary baseline for any digital asset investigation resides on the public blockchain. Key evidence elements include:
- Cryptographic Transaction Hashes (TXIDs): Definitive, unalterable proof of token transfer from the insured's control addresses to unauthorized third-party wallets.
- Smart Contract Execution Traces: Internal transaction traces showing exploit execution, flash loan mechanisms, or permission approval manipulation.
- Cluster and Entity Attribution: Forensic mapping showing whether stolen funds flowed into known mixer protocols, cross-chain bridges, or centralized exchange deposit infrastructure.
2. Off-Chain Operational and Server Audit Trails
While on-chain data proves *that* funds moved, off-chain data proves *how* access was gained. Critical items include SIEM server logs, CloudTrail entries, VPN authentication logs, and hardware security module physical access logs. Insurers cross-reference these records to ensure internal security warranties were not breached at the time of loss.
3. Proof of Initial Control and Cost Basis Documentation
Underwriters require verified proof that the policyholder held clear legal title and absolute control of the underlying assets prior to the event. This includes historical purchase receipts from compliant exchanges, signature verification tests, and original wallet initialization records. For legal teams managing corporate claims or crypto recovery in South Carolina and across other US jurisdictions, presenting verified chain-of-custody documentation is vital when framing insurance claims or supporting legal actions.
To understand the depth of technical proof necessary when presenting findings to third-party adjusters or judicial authorities, review our comprehensive master guide on how to trace funds after a scam.
Frequently Asked Questions Regarding Crypto Insurance Evidence
What proof of loss do insurance underwriters require for crypto theft claims?
Underwriters require proof of control over affected wallets, detailed on-chain transaction hashes, server access logs showing unauthorized intrusion, and a formal forensic report establishing that the loss resulted from an insured event rather than insider collusion or negligence.
Can an insurer deny a crypto claim if private key security protocol was breached?
Yes. Underwriters closely review internal security protocols against warranty representations made during policy inception. If evidence demonstrates failure to maintain required hardware security modules or multi-signature controls, underwriters may issue a reservation of rights or deny coverage outright.
How do forensic experts verify that an attack was external rather than an insider theft?
Forensic investigators analyze system login times, IP geolocation data, identity access management logs, and multi-signature key share usage. By comparing compromised key locations against authorized employee access patterns, investigators establish whether credentials were extracted via external malware or unauthorized internal access.
What Victims and Legal Counsel Should Do Next
If your organization has suffered an asset loss subject to an insurance claim, taking immediate, structured action is critical to preserve your coverage rights and maintain claim validity.
- Preserve All Logs Immediately: Secure server images, API gateway logs, firewall telemetry, and device volatile memory without modifying file system metadata. Avoid rebooting core infrastructure until forensic snapshots are secured.
- Execute Immediate Threat Containment: Revoke compromised API keys, rotate remaining multi-signature key shares, and isolate remaining digital assets into clean, cold-storage environments as detailed in our guide on wallet compromise immediate response.
- Engage Independent Forensic Experts: Retain independent blockchain forensic experts to perform an unbiased technical reconstruction. Underwriters scrutinize self-prepared internal reports heavily; third-party verification provides objective credibility.
- Review Policy Warranties and Frame the Notice of Loss: Work alongside legal counsel to review your specific policy wording, insuring agreements, and exclusions before filing formal proof of loss. Ensure technical findings correspond directly to policy-defined covered perils.
Warning on Fraudulent Recovery Services: Beware of illicit online services promising guaranteed recovery of stolen cryptocurrency for upfront fees. Blockchain forensic investigation establishes objective facts, traces asset destinations, and strengthens legal and insurance claims. No legitimate firm can guarantee the physical return of funds.
To evaluate your evidence standards or retain expert forensic support for an active insurance claim, contact our specialized investigative team through our secure intake portal at Aegis Financial Forensics Contact.